
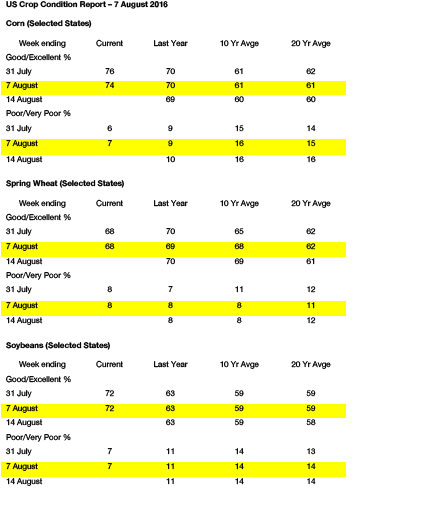
- Chicago markets started the day with grains either side of unchanged and soybeans extending their rally on continued strong Chinese demand and an expectation that the USDA figures on Friday will show a substantial reduction in 2015/16 end stocks on the back of increased export demand. The trade is braced for a 2016 US corn yield of 171-174 bushels/acre with some even higher than this, consequently the potentially record US corn crop is weighing on prices.
- Brazil’s CONAB reported a slight reduction in their 2016 soybean and corn crops with soybeans pegged at 95.4 million mt vs. 95.5 million in July with corn at 68.5 million mt vs. 69.1 million in July. Despite the reduction being close to expectation, it should be noted that output is inching ever closer to domestic usage and fob premiums are rising to levels now some $0.40-$0.60/bu above other origins. The positive spin is that with cash corn prices in Brazil reported to be as much as 70% above last year we should anticipate some significant expansion in new crop acreage.
- The markets are now looking for objective N Hemisphere yield data and some indication as to whether, or not, production gains can keep pace with improved export demand specifically as far as US soybeans are concerned. We would expect the US corn market to stabilise at its multi-year low levels as growth in stocks to use appear to be less than initially feared as the US’s share of global export trade has the potential to improve. As we write this it seems that even high quality wheat is starting to attract attention from major importers with the prospect of a further widening in premiums for milling grades over feed supplies.