20 June 2015


Weekly CCI Analysis:

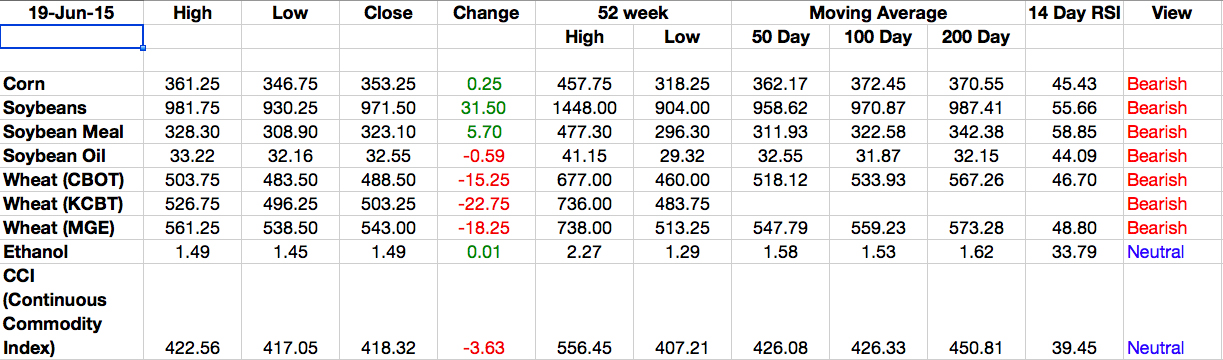
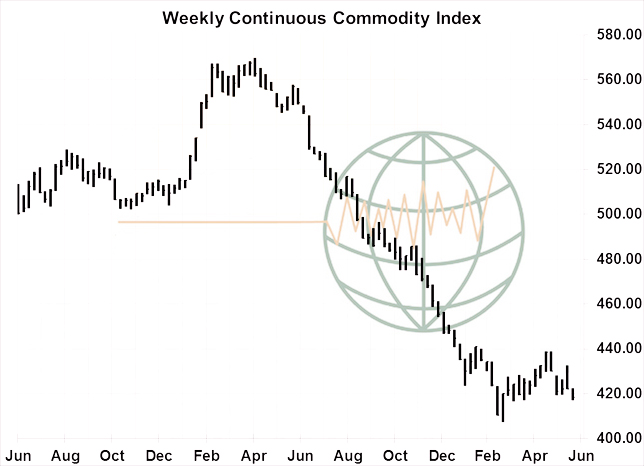
The CCI/CRB index finished the week lower even with a fall in the US$ on sliding grain and energy prices. The week ahead will be important as fund managers head into the end of the month and quarter. Amid US and Asian equity prices that are pushing to new record highs, commodities as an investment continue to fall out of favour. The recent rally in the CCI index appears to be corrective in nature and the US$ should rally regardless of the outcome of the Greek debt payment which is due on June 30th. At a minimum, the CCI index should retest contract lows by late summer or early autumn. Our view continues to remain bearish commodities. The world energy market should have scored its seasonal high with WTI crude above $62. A lower close in the week ahead would be deemed bearish heading into July.
Longer-term soybean analysis:

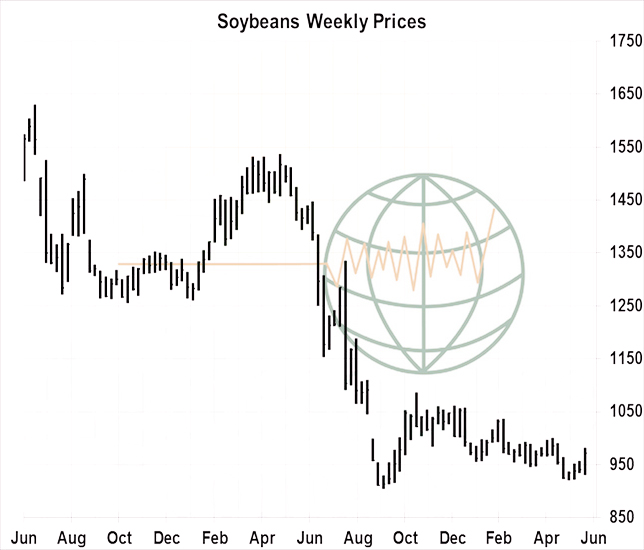
Soybean futures ended the week higher with fund short covering ahead of the end of month USDA reports being the main feature through the week. New crop soybeans fell to new contract lows which could not be sustained. This triggered short covering and a technical rally unfolded for the remainder of the week. The market is concerned that excessive rains in some areas of the country will reduce total acres. However, planting progress is expected to surpass 90% by Sunday, while crop condition ratings are expected to hold at a historically high level. Old crop June 1 stocks are projected at an 8 year high, and our view remains bearish. Saturday’s weather forecasts are much improved for the seeding states of KS and MO. A lower start is expected on Sunday with a resumption of the bear trend expected as US crushers added 2-3 weeks of cash inventory and have covered their crush needs into early to mid August. A cash lead decline is in the making.
Longer-term corn analysis:

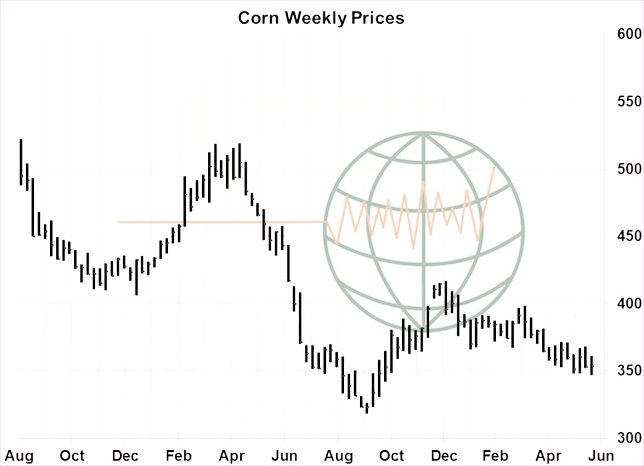
Corn futures this week ended unchanged. Strength was noted early, but US favourable longer term weather forecasts continue to trump uncertainty ahead of NASS’s Stocks and Seedings report. Heat/dryness is noted across the Delta/Southeast, with modest yield loss likely. But this will be offset by near record high crop ratings across the Central Corn Belt. NOAA projects July to be cool/wet across the whole of the Central US – driven by El Niño – and the trade is well aware of the positive effect cooler than normal temperatures have on Midwestern ear weights. Some weather premium was added early in the week, but potential for record/near record yields remain. Otherwise, little has changed. Gulf corn becomes uncompetitive beyond July. Black Sea weather is improving. June 1st stocks are projected some 850  larger million bu than last year. We maintain spot and new crop futures will drift slowly lower if favourable weather is confirmed beyond July 1.
Longer-term wheat analysis:

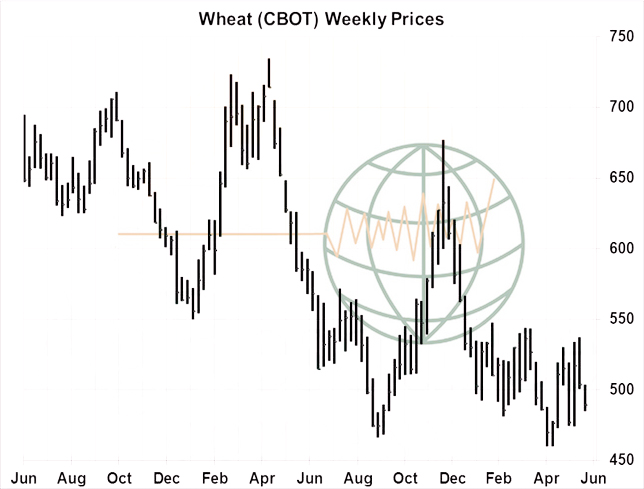
Wheat futures ended down 15-23 cents, with HRW contracts pacing the decline amid favorable S and C Plains harvest weather projected into the end of June. Much of Western and Central Europe has benefited from needed rainfall in the last 5-7 days, while Australia – despite El Niño – has seen soaking rainfall in the East, with similarly heavy rains offered to Western Australia in the coming days. With funds having liquidated a sizeable portion of their net short position in mid-June, it’s back to fine-tuning world production figures and determining just how much the Black Sea will export in the next 4- 5 months. World fob price spreads have narrowed, but a range of $4.50- 4.70, basis spot Chicago, is needed for Gulf SRW to compete against Russian and EU origins. US HRW is still a long ways off from finding any non-traditional business. Seasonal lows lie in the offing, but rallies will be hard-fought without extreme heat/dryness across Argentina and Australia in Aug/Sept. Rallies to $5.30-5.40, basis Chicago, are opportunities to catch up on 2015 and 2016 forward sales or to open/add to short positions.
18 June 2015

  • Chicago trade has been mixed with fund buyers once again evident on technical trade. Questions remain over whether or not the recent wet conditions will adversely impact acres or yields. Fund, who have been net short to a sizeable degree, have been buyers and this is countering cash selling by farmers. A weaker US$ has also added a touch of market support.
  • US weather looks as if the worst of the rains will end as tropical storm Bill passes through the Ohio Valley within the next 48 hours. Rains have reduced but already saturated soils has left some ponding and low level flooding. Will this be a serious negative to yield? Time, as always will tell, but the old adage of “rain makes grain” still sits in the forefront of our mind right now.
  • The USDA has today released its weekly export figures as detailed below:

Wheat: 315.900 mt, which is within estimates of 200,000-400,000 mt.
Corn: 827,600 mt, which is above estimates of 450,000-800,000 mt.
Soybeans: 664,900 mt, which is above estimates of 250,000-600,000 mt.
Soybean Meal: 176,300 mt, which is within estimates of 50,000-250,000 mt.
Soybean Oil: minus 100 mt, which is below estimates of zero-10,000 mt.

  • The above numbers were unsurprising given that US wheat and soybeans look uncompetitive into October! Brazil will doubtless be a massive exporter of corn for the coming six months, which will be a drag on further US corn sales.
  • Brussels has issued weekly wheat export certificates amounting to  385298 mt, which brings the season total to 32,481581 mt. The season to date total is now 3.355 million mt (11.52%) ahead of last year.
  • Our overall outlook suggests that as the N Hemisphere wheat harvest is almost here, despite some ongoing  issues,there is little to suggest that a major reversal of price trend is under way. In corn next week’s US weather forecast for warm and dry conditions will be very welcome, and needed. The cooler and wetter 8-15 day outlook should also be viewed as favourable as the crop moves into its pollination phase. The appears to be plentiful US stock and the recent rally in corn looks to be less solid than in soybeans. Each year, almost without exception, we see a market phenomenon known as a weather market, prices moving up and down on whatever the current forecasts bring – exacerbated by fund orders. Our view is to “sit it out” until after the June stocks report and possibly even two weeks into July. Remember last year’s 70 cent plunge in prices – and the regrets of those who jumped too soon!

18 June 2015

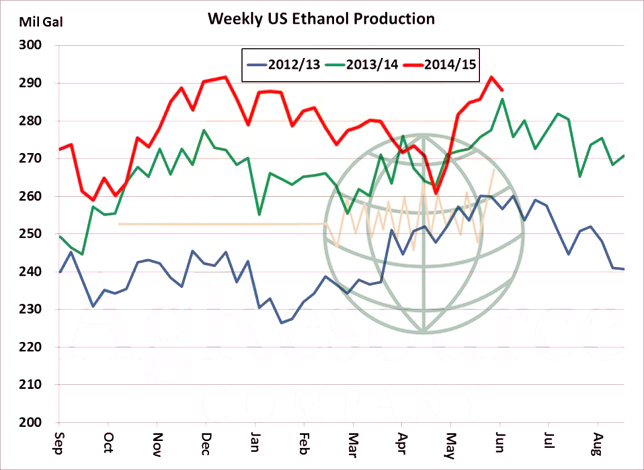
The weekly US ethanol grind continues slightly above pace needed to meet the USDA’s forecast. But stocks remain some 16% above last year, ethanol margins are in retreat amid sliding DDG and ethanol prices, and production seasonally peaks in mid to late June. A slow drift lower is expected in coming EIA reports, and the USDA was justified in lowering its projected corn used for ethanol production in its June WASDE.

A more in depth review of the US soybean stocks position follows:

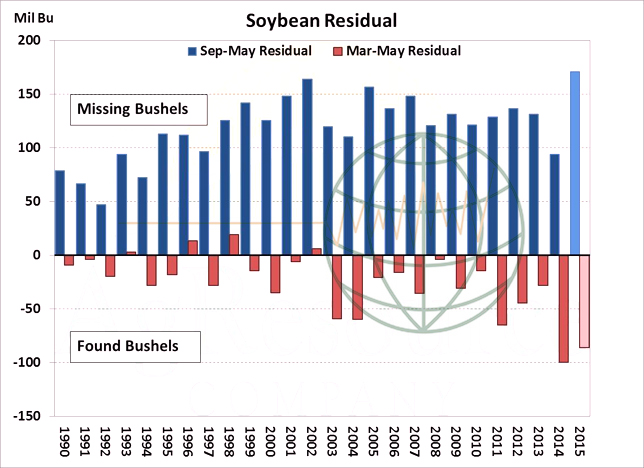
We estimate June 1st soybean stocks at 683 million bu, up 278 million bu or 69% from a year ago. If realised, US soybean stocks at the start of the 4th quarter will be at an 8 year high and at the largest level since 2006. Based on NOPA data, we estimate a quarterly crush rate of 483 million bu, while Mar-May exports are estimated at 180 million bu. The combined usage total of 663 million bu is up 6% from last year and largest since 2011. June 1 stocks as a ratio of Sep-May use is projected at 21% versus 13% a year ago and the 5 year average of 19%. Increased year on year supplies are reflected in both Midwest cash basis and flat prices. Basis across the Cornbelt is at 3-4 year lows, while flat price at mid-June is nearly $5/bu cheaper than a year ago. Exports will remain very slow through the summer, while crushers will be adequately supplied. Farmers are thought to be sitting on a huge amount of old crop bushels, which will likely cap summer rallies.

With crush, exports, and imports approximately known ahead of the report, the only variable left to estimate for the quarterly balance sheet is the quarterly residual use. It is the residual component that has produced such variability in quarterly stocks reports in recent years. The December and March reports collectively hinted that NASS had overestimated the 2014 soybean crop, and the Mar-May residual rate will offer more evidence as to whether this is true. Missing bushels in the first half of the year were record large at 257 million bu and we anticipate that the majority of those bushels (224 million) will be found in the last half of the year. The Mar-May residual rate is estimated at -86 million bu, with a near record low 4th quarter residual total of -138 million bu to be confirmed in the September stocks report.

17 June 2015

  • It has been another day of gains in Chicago as the trade debates what could wet weather mean for US seedings and yields in both corn and soybeans. Some ponding and low level flooding was noted last year in mid-June across Iowa and E Nebraska with this year’s flooding taking in N Illinois and parts of W Indiana. It will be the weather next week that will be key in terms of a needed warm/dry period. On the bright side, Midwest soil moisture levels are estimated to be the best since 2010 but there seems to be agreement that recent rains have taken the edge off yields in MO, IL and IN.
  • Overnight saw China announcing that it is scrapping its programme to stockpile rapeseed/canola and will offer growers subsidies instead, starting with their imminent harvest. This seems to be a replication of what happened last year in soybeans and cotton in that the government no longer wants to offer high minimum prices and consequently build their own domestic stockpiles. The news is bearish for global rapeseed/canola and it begs the question, are the grains going to follow in terms of reduced minimum pricing.
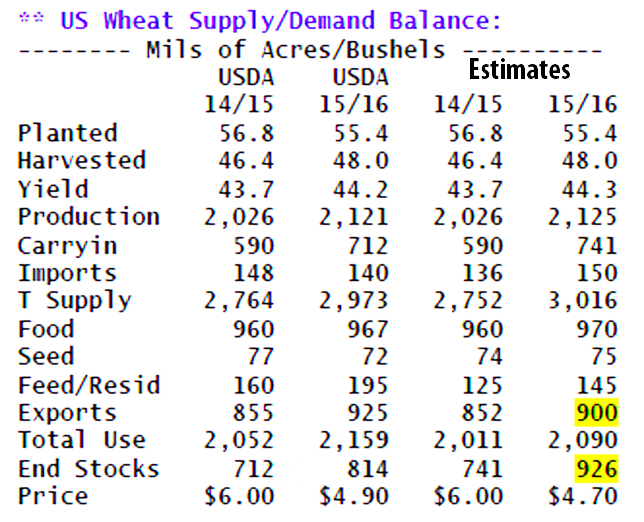
  • A more in depth review of the US wheat stocks position follows:

  • The highlighted 2014/15 line in the table above projects final 2014/15 US wheat ending stocks at 741 million bu. This is up 29 million bu from the USDA’s forecast in its June WASDE and down just marginally from prior estimates due to lower projected imports in the Mar-May quarter. Year-end stocks of 741 million bu are the largest since 2011, while annual stocks/use at 36.8% is the largest since 2009. Lofty stocks are well known, but the issue ahead is that stocks will continue to build. US wheat is in a demand-led bear market.
  • We peg final 2014/15 exports at 852 million, down just slightly from the USDA’s 855. Final imports are estimated at 136 million bu, vs. the USDA’s projected 148 million. However, we expect feed use in the final quarter to be heavily negative, with the USDA’s annual feed/residual forecast some 35 million bu too high. There’s no shortage of wheat, and even early harvest reports across the far Southern Plains have been encouraging. Moving forward, we are in agreement with the USDA’s production estimate, though there’s room to grow the spring and durum harvests amid normal summer weather. However, it is demand that remains overstated – exports in particular! US exporters will struggle to reach even 900 million bu in 2015/16, and total consumption in the coming marketing year is expected to grow by just 4% – while the total US wheat supply will increase 9%.

  • The graphic below illustrates current world fob price relationships for delivery in the July-September period. Like the past12 months, US Gulf wheat is poorly positioned to sell anywhere outside of already captive markets (favoured nations in E Asia, Africa and the W Hemisphere). Gulf SRW is even priced near parity with much better quality German origin into August, and HRW is offered at a lofty premium of $34-46/mt ($.90-1.00/bu) to all other origins. A year ago, US wheat was far more competitive and without a crippling drought in Australia in September, US exports may even decline on the year (sub 850 million bu) taking 2015/16 US wheat stocks near 1,000 million bu. It is stocks/use, rather than simply stocks, that will cap rallies above $5.25 spot Chicago, into late 2015. Harvest lows could form near $4.40-4.60.

  • Finally, the German Co-op association has downgraded their crop estimates on account of dryness as follows:

  • The above data has brought some further focus to the trade, particularly to dryness is N France where conditions have arguably been dryer than in Germany, and shows little relief in the next 10-14 days. If the downgrade in the German crop was replicated across the whole EU we would be facing a 12 million mt crop reduction (vs. the USDA’s 6 million mt). Clearly the other side of the equation remains, where is the demand, and this is perfectly valid – but do not underestimate the farmers willingness to “shut up shop” in the face of a crop issue – if that is what we are about to see.

16 June 2015

  • Turnaround Tuesday folklore comes to life once again as soybeans see short covering offering support. Yesterday’s failure to close at a new low saw the bulls emerge from their lair. Slightly lower soybean seeding progress in KS/MO despite a drier forecast saw prices higher.We doubt the market’s ability to maintain upward momentum as the forecast suggests dry and warm conditions next week. Plentiful soil moisture levels also suggest that there is little to raise concern over planting delays across MO and KS.
  • Corn and wheat prices have lagged behind the soybean rally as the wheat harvest is only just around the corner and most of the corn acres are now planted. Weather forecasts have little, if anything, in the way of extreme heat to disrupt pollination, which could prolong any rally.
  • More topically today is tropical storm Bill that is hitting the headlines. The remains of the storm are looking likely to push through the E Plains and into AR/MO as well as S IL. Heavy rainfall is likely across the E Plains with maybe 0.5”/2.5” across MO, IL, IN. Warmer and dryer conditions are forecast to follow, which will aid both planting and crop development.
  • Matif wheat and corn markets have been described as “desperately” quiet as AgriMer forecast lower French wheat stocks for 2014/15 at 3 million mt, 600,000 mt below their last estimate, as EU export volumes continue to flow at a rapid pace. The volume of French soft wheat exports (non EU) is put at 11.1 million mt, up from 10.6 million mt previously estimated.
  • To conclude, a couple of longer term thoughts suggest that in wheat, projected Russian wheat output at trend yield, which is 5% below last year together with the USDA’s area forecast gives an output of 59.5 million mt. The USDA’s latest forecast of 55 million mt suggests a 12% decline in yield year on year. Few suggest that this is likely this year. In corn, there is no immediate weather issue and US farmers continue to hold large old crop stocks. S American corn will be coming to market at the same time as the US harvest! In soybeans we can find little evidence that the “big picture” has changed.

16 June 2015

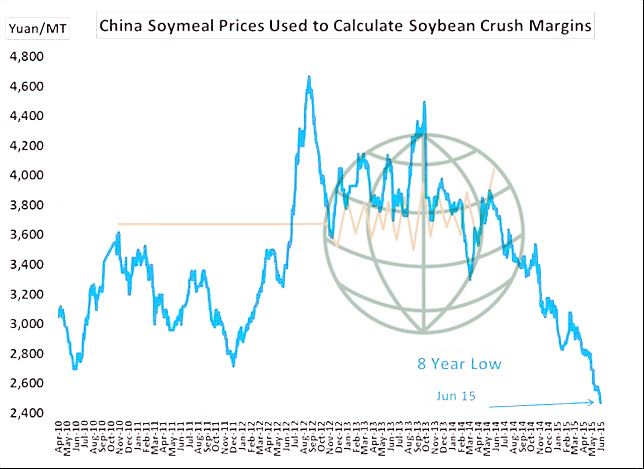
The Chinese soybean meal market has accelerated its decline and most market sources now argue that China will have to more aggressively export soybean meal to rid itself of excess supply. With record soybean imports arriving, this may take until the end of the summer. Chinese soybean meal prices now rest at an 8 year low and there is no bottom in sight with cash defaults accelerating. Falling soybean meal prices in China (and around the globe) are likely to pressure crush margins. This looks like the last supportive peg for $9.00 spot CBOT soybean futures.

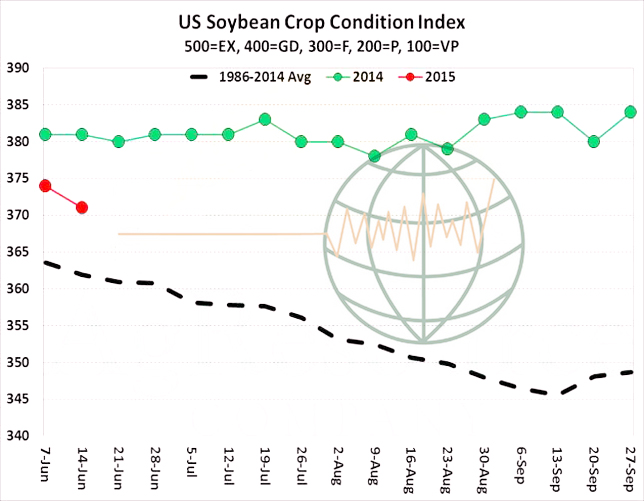
NASS reported soybean planting progress on a national basis advanced to 87%, with 11 states more than 90% complete. National crop ratings were little changed, with good/excellent down 2% at 67%, while the index of all crop ratings was down slightly. As seen in the chart below, the index of all ratings continues to reflect a very high rated crop and we see no reason to disagree with the June WASDE yield of 46 bu/acre. With adequate old crop stocks and favourable new crop ratings, we hold to a view of selling rallies for a decline to $8.40-8.60 by mid to late July.

Corn crop conditions as of Sunday were pegged at 73% good/excellent, down 1% from the previous week. Declines of 2-8% are noted across the E Corn Belt due to wet weather. Note that IA’s crop improved 2% to 82% good/excellent. Modest boosts also occurred across the S and C Plains. Some yield projection models maintains a forecast of 166-169 bu/acre! The crop is 30-90% silking across TX & the Delta/Southeast. Steady/higher conditions are expected into late June as excessive precipitation ends beyond the next 3-4 days.

NASS’s weekly wheat crop update featured only minor changes to US wheat conditions. Winter wheat is rated at 43% good/excellent, unchanged from the prior week. The largest downgrades occurred across the S and E Midwest amid excessive rains. PNW ratings improved 2%. Spring wheat is rated at 70% good/excellent, up 1% point on the week amid small improvements in the Dakotas. US winter wheat is 11% harvested, vs. 15% last year, though this progress will accelerate into late June amid reduced precipitation and at least average temperatures.

Dryness concerns in Europe have eroded, and now include just portions of Germany and N Poland. Canada will see normal to above normal precipitation through the next two weeks. Moderate to heavy rains are scheduled across Eastern Australia in the next 48 hours, and so major world production threats are lacking.

Finally, recall that through the week ending June 11th, funds in the US liquidated a sizeable portion of their net short position. It is now back to monitoring the Black Sea’s surplus in determining ultimate seasonal lows in world cash market. A retest of $4.60-4.70 spot Chicago futures is expected in the next 2-3 weeks. Short covering rallies will be capped above $5.10 basis July Chicago.

15 June 2015

  • The week has started generally lower, CBOT and EU markets all saw losses in some shape or form. Wheat and corn led the way lower in Chicago whilst July soybeans traded either side of unchanged and the new crop was pressured by favourable weather conditions. Front month wheat in Chicago broke below its 50 day moving average triggering further sales including funds. If fresh seasonal lows are scored we will doubtless see additional fund participation with further selling. July corn tested and made fresh contract lows although it actually closed at a level equal to the previous contract lows. The signs look strong for a retest in coming days.
  • There have been rumours of additional Chinese DDG defaults as Chinese importers experience “difficulties” in opening Letters of Credit. There are suggestions that China is preparing to drop the minimum corn price loan to farmers and offer a heavily subsidised rail price to allow movement of corn stocks from the heavily stocked NE into the SE of the country. Importers and end users are consequently more cautious on new purchases as well as shipping of existing contracted purchases. Soybean meal prices in China slipped again to a fresh eight year low.
  • Australia’s ABARES issued a revised 2015/16 wheat crop forecast 800,000 mt lower at 23.6 million mt. They also reduced their canola (rapeseed) forecast by 290,000 mt to 2.97 million mt. Both reductions were attributed to the onset of El Niño conditions, which are expected to impact output negatively with its likelihood of dry conditions.
  • France’s AgriMer placed the wheat crop at 87% good/excellent, which is a 2% reduction week on week although an improvement from 73% year on year. Winter barley, which is due to begin harvest any day now, was also rated 2% lower week on week at 86% good/excellent. Spring barley saw a bigger reduction at 86% good/excellent, down from 91% week on week. Corn was rated 84% good/excellent, again a 2% week on week reduction.
  • European weather conditions saw rain continuing to push north today as only the northers third of France, N Germany and NW Poland without. The rain is forecast to move east bringing significant precipitation on Tuesday into the Balkans and W Ukraine. This is expected to continue Wednesday leaving most of Europe dry. Thursday and Friday sees significant rain in N Germany, Denmark and Poland and N France appears to have to wait until the weekend to see any volume of rain. Fortunately, there is a lack of any appreciable heat, which could be damaging in dry conditions. S Russia appears to be blessed with regular rainfall most of the week. All in all, the forecast appears to be beneficial to current crop production.

13 June 2015

Weekly CCI Analysis:

The CCI/CRB commodity index tried to rally this week, but failed on the prospect of rising US interest rates and a stronger US$. The US FOMC will be meeting this next week to decide when US interest rates will start to be normalised. The expectation is that the US Central Bank will hold rates steady, but it will suggest that the first US rate change in 6 years will be offered during either the September or December meetings. The US$ rallied on the prospect of a rate rise while Greek debt repayment remained a worrisome event for the European Central Bank and the IMF heading into the end of June. Research maintains that crude oil is caught in a range of $48-64.00 into year end and we remain sellers above $62.00. A seasonal high should be forming in crude which will allow the CCI index to forge new lows by late summer or early autumn. We are bearish the CCI on rallies

Longer-term soybean analysis:

Soy futures finished the week mixed with old crop beans fractionally higher while November was slightly lower. The June WASDE did not hold any bullish surprises, and market focus is on new crop conditions and global trade/price trends. China continues to suffer from soy oversupply and both spot and forward crushing margins turned negative for the first time in over a year. S American premiums on beans and meal both continue to work lower offering an import chance into the US. Planting progress through Sunday night is expected to reach 86-88% while crop ratings will remain historically strong at 69-71% good/excellent. Without a major weather threat, the outlook for the soy market remains bearish amid excessive supplies and record large new crop production. Our downside price targets for July rest at $9.00 and $8.40-8.60 November for a summer seasonal low. During harvest Nov could slide to $8.00.

Longer-term corn analysis:

CBOT corn futures settled the week down 7-9 cents in old and new crop positions. The highlight this week was a higher Brazilian corn estimate (81 million mt) from both the US/Brazilian governments and additional hikes are expected in the coming months. S American corn production in 2015 will be record large, and exporters there will begin to dominate world trade by late July/early August. USDA also raised US corn stocks modestly on a lower projected industrial use due to this year’s surge in ethanol yield. There is a concern over too much rain scheduled in the next 3-4 days across E KS, IA and MN, but we can find no real correlation between excessive June precipitation and final US corn yield. The broad theme of 2015/16 will again be huge competition in world feedgrain trade, which based on fob relationships will favour S America beyond the next 20-30 days. We maintain that short covering rallies should be used to extend or make forward sales. The risk is sub-$3.00 Dec corn at harvest amid lacking US demand growth and strong yield potential. Spot corn rallies will likely be limited to $3.70 without the unexpected development of a dire US/Chinese drought.

Longer-term wheat analysis:

US and European wheat futures ended down on the week as the USDA hiked major world wheat exporters’ production – including the US – in its June WASDE. The highlight was the 2.5 million mt rise in the Black Sea harvest, which was put into exports. This will keep fob offers depressed throughout the coming months. Black Sea prices are the world’s benchmark in the first half of the crop year, and Russian wheat continues to be sold into N Africa at $190/mt or below. This is comparable to $4.60-4.70, basis spot CBOT. Weather is improving across France, S Germany and whole of the Canadian Prairies, and without dire weather in Australia or Argentina, global wheat stocks look to exceed 200 million mt in 2015/16. The goal of the market is to elevate US wheat exports or the US will be left with end stocks near 1,000 million bu. A range of $4.50-5.25 is indicated into late 2015. Wheat quality across the far S Plains (TX/OK) has been reported to be above miller’s expectations.

13 June 2015

Chinese soybean crush margins in both a spot and forward positions have slipped to negative levels for the first time in a year. Chinese cash soybean meal has imploded in recent months to their lowest price in 8 years! In fact, the spread between Chinese soybean meal vs. the US Gulf is at a record low premium of just $32/ton Chinese premium. China is more aggressively offering meal for export into SE Asia which relative to the US, is competitive. The Chinese crush is seasonally ramping up.