11 September 2013

  • As expected, today has seen little action in the run unto tomorrow’s USDA crop report. Nervous traders have probably reduce position size ahead of the report in a “risk off” mood. We have reported in recent days our view that global crops show a stock rebuild potential and despite some reduction in predicted northern hemisphere output we continue to stare at increased total supplies of both grains and oilseeds, which will impact S&D and in turn prices. Our S American contacts advise us directly that oilseed planting intentions are for increased acres assuming weather permits, and hot on the heels of increased northern hemisphere output it would seem likely that our high school economics lessons will prove correct and drive prices in a downward direction, unless of course we can see demand escalation of some magnitude (from where, we know not).
  • Lanworth, the Reuters crop forecasting arm, today increased global corn output to 942 million mt (from 940 million mt) due to improved prospects for crops in both the US and Ukraine. Ukraine output was increased 3% to 26.4 million mt as a consequence of “moderately wet and unexpectedly cool” late August weather. The US output was put at 13.396 billion bu based upon a yield of 152.2 bu/acre. The latest figure is an increase from their last estimate of 13.330 billion bu and 151.6 bu/acre. Their outlook for soybean output was less optimistic with US production trimmed marginally to 3.113 billion bu (from 3.114 billion bu). Global wheat and soybean output were left unchanged in their latest deliberations (at 702 million mt and 278 million mt respectively).
  • Tomorrow looms large although historically it is the next, October, report which has produced market upsets. However, the USDA has in recent times had sufficient lack of predictability to see an apple cart or two being upset and tears shed as their reports are read.

10 September 2013

  • Today has seen another Egyptian purchase of wheat, unsurprisingly from the Black Sea! This time, the fifth since late August, 115,000 mt went to Ukraine and 60,000 mt each to Russia and Romania. French offers were some $3/mt higher on an FOB basis, but the additional $6 or $7 on freight meant they were close to $10 out basis C&F.
  • In France, cash premiums for wheat declined as their estimated output was increased by 900,000 mt to 37 million mt, which compares with 35.5 million mt last year. (This figure is still lower than a number of private estimates.) Th bigger picture suggests that a larger EU crop will result in a lower need for French imports and the increased French crop has left the trade talking of a 12 million mt exportable surplus, an increase of 2 million mt over last year.
  • Whilst EU exports are running over 2 million mt ahead of last year the French share is only 400,000 mt of this. The lack of competitiveness in Egyptian tenders will leave the S&D heavy on the supply side!
  • Other news includes the increased forecast by Brazil’s Conab (government crop supply agency) in 2012/13 corn output to even higher record territory, their latest estimate has reached 81.3 million mt, an increase of 1 million mt from their August estimate. At the same time they reduced the 2013 wheat crop estimate to 4.95 million mt from 5.62 million mt.
  • Brazil has expanded a duty-free wheat import quota through to end November by 400,000 mt after severe frosts blanketed the country’s main wheat belt in the past two months and as its main supplier Argentina is struggling with its own shortages. The expansion takes the quota to 2.7 millions mt. Brazilian flour mills have already purchased 2.3 million mt of US and Canadian wheat for import under the quota, which exempts the wheat from a common import tariff of 10 percent. Brazil is often among the top two or three wheat importers in the world. As members of the Mercosur customs union, grain trade between Brazil and Argentina is tariff free.
  • We, like the rest of the trade await the USDA report which is scheduled to be published at 5pm (UK time) on Thursday.

9 September 2013

  • We start the week in a quiet manner in what is almost guaranteed to be a quiet run up to the USDA’s next, and much anticipated, report on Thursday.
  • Front month contracts in Chicago are soon to expire, and with cash premiums evaporating fast as newly harvested crops reach eager customers, the futures have faded fast. Buyers are reluctant to purchase more than immediate requirements and the old crop premium will now be very short lived.
  • We can see a scenario building where season highs have been scored, grains (corn and wheat), as we have reported previously, would appear to struggle to make significant gains in the light of global supply rebuild and soybeans have a similar uphill battle in an enlarged world supply situation.
  • There appears slightly more rain in US forecasts and, encouragingly, there is little in the way of a damaging frost forecast through to the last week of the month.
  • We continue to look forward to Thursday’s figures with interest.

5 September 2013

  • What goes up must come down, or so it seemed this morning! Tuesday’s gains in soybean meal were retraced yesterday and again this morning, although late trade has seen the soybean complex back into positive territory; the grains have continued weak, and this has spilled over into European grain markets.
  • Of interest is the level at which yesterday’s Egyptian purchase was made, the Black Sea seller’s level basis C&F was $7 below the US soft red wheat FOB level. This illustrated the disparity between origin offer at the present time, which will surely be rectified in time. The question will no doubt be, “Will Black Sea offers rise as availability is reduced, or will US prices fall to become more competitive?”
  • Brussels has issued wheat export licences this week for 558,695 mt bringing the season total to 4.686 million mt, 2.3 million mt ahead of last seasons figure.
  • The market remains nervous as weather forecasts vacillate between dry and wet and the USDA/WASE report looms ever closer next week with all it may bring with it. Within days we will see the FSA acreage report updating figures and shortly after we will see actual harvest results. It is only then that we will be able to judge what effect the weather conditions have actually had upon yields.
  • Commodity broker, F C Stone, has released its latest crop estimate with a corn yield of 156.4 bu/acre giving an output of 13.942 billion bu, this compares with the USDA’s latest 154.4 bu/acre and 13.763 billion bu. Their soybean numbers came in at 41.2 bu/acre with output at 3.146 billion bu vs. USDA figures of 42.6 bu/acre and 3.255 billion bu. Bear in mind the USDA will update its numbers on 12th September. For comparison Allendale forecast corn at 153.4 bu/acre and soybeans at 39 bu/acre whilst a Reuters survey saw corn yield at 153.985 bu/acre.

4 September 2013

  • The markets have today all traded lower with funds being noted sellers in the soybean complex as well as in grains. The inability of the Nov ’13 soybean contract to push into new highs has been cited as the trigger for selling of a technical nature. As ever, the grains tagged along with the decline.
  • Egypt’s GASC once again secured wheat in their most recent tender, this time for October 21-31 shipment. Russia secured 120,000 mt and Romania the balance of 60,000 mt. This brings Egypt’s 2013-14 procurement to just over 1.9 million mt, and is the third such tender within eight days. Perhaps of interest is the growth in tonnage secured by Russia who were noticeable by their failure to secure early tonnage in Egypt’s tenders. France, once again, was too expensive and failed to secure a sale.
  • The Reuters crop forecasting arm, Lanworth, once again cut its forecast for US corn and soybean output as a consequence of hot and dry conditions. Corn was forecast at 13.33 billion bu with yield at 151.6 bu/acre, which is a reduction from 13.406 billion bu and 152.4 bu/acre. Soybeans were predicted to yield 40.4 bu/acre with a total output of 3.114 billion bu, which compares with 40.8 bu/acre and 3.14 billion bu last estimated. In the same report they increased global wheat output to 701.84 million mt (3 million mt increase month on month) based upon improved prospects for crops in Russia, Canada, Kazakhstan and Argentina, which are expected to offset the poorer outlook in Australia.
  • Much has been talked of the US weather conditions of late. The season started late with unusually wet conditions delaying seeding in sodden fields, although some heroic efforts were made by farmers to catch up when conditions allowed. Crops (corn and soybeans) became tested as conditions moved towards the now all too familiar dry state. We are all familiar with the adage that corn crops are made in July, and soybeans in August; helpfully for corn, the dry spell only really kicked in in late July, which means that the corn crop has escaped the worst yield influencing impact of the dry weather. More concerning is the August dryness which is impacting soybean crops.
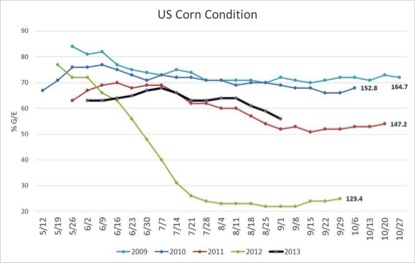
  • Yesterday’s (Tuesday) crop condition report showed corn good/excellent rating on 56% of the crop, much as expected, down from 59% the previous week and way ahead of last year’s drought hit 22%.


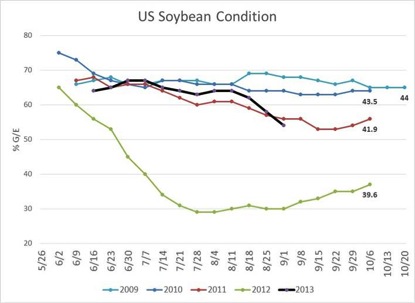
  • The condition of the soybean crop was reported as 54% good/excellent, again this was as expected, down from 58% week on week but an improvement on last year’s 30%.


  • It must be remembered that last year’s drought hit much earlier and the corn crop suffered in the key pollination stage of growth, and that late rainfall (in August) boosted soybean output – see old adage above! Regardless, the outlook for both soybean and corn output remains above that of last year.
  • S America soybean stocks are reducing swiftly as the strong pace of world demand (China) boosts exports. August soybean exports from S America rose by nearly 4 million mt year on year, with Brazil accounting for 3 million mt and Argentina 0.9 million mt. September export volumes are also expected to be higher than last year, largely as a result of low availability of US stocks and late availability of new crop due to the likely lateness of harvest. The key question will be, “Can the US deliver sufficient volume of soybeans to export locations to satisfy global import requirements from October?”

3 September 2013

  • The day, and holiday shortened week, started out with CBOT prices sharply higher on the back of limited rainfall in the ten day forecast for central US cropping regions. With soybeans the most needy for moisture it was little surprise that they led the pack higher with Dec ’13 soybean meal trading limit ($20/ton) up early on. Corn and wheat tagged along. By mid-afternoon (UK time) the meal contract had given back $6 of its gain and the grains turned into negative territory.
  • The long weekend weather, which was always going to be watched closely, contained varied rainfall in terms of both quantity and coverage. Some areas received more than anticipated whilst others received less. The forecasts for the next week to ten days offer some limited rains across the central and south Midwest with the possibility of some falling across the northern parts of the Midwest. We have seen forecasts of rain failing to materialise in recent weeks and until there is rain in the gauge we doubt traders will ease up on their endeavours to prop up prices, particularly in soybeans and meal.
  • It becomes harder, as time marches onwards, to continue to believe that the world is well supplied with grains and oilseeds (as we have frequently stated). However, the potential crops in the US, following on from S America’s harvest and their upcoming planting intentions, which are being talked up, suggests that our view remains plausible. We will continue to stand by this position for the time being.
  • Today Stratégie Grains revised their projection for the French maize crop which has benefitted from warmer temperatures permitting a degree of “catch-up”. Their revised estimate at 15.6 million mt is nearly 360,000 mt below their last figure issued on 9 August. Yield at 8.8 mt/ha is lower than the 9.14 mt/ha previously forecast although the acreage has been increased slightly, which offsets some of the yield decline. If achieved, the revised forecast tonnage will almost equal last season’s output.
  • With yesterday being a holiday in the US we did not report on the latest wheat tender by Egypt’s GASC, who secured a further 355,000 tonnes for 1-10 October shipment. The “usual suspects” were successful, Romania with 120,000 mt, Ukraine with 60,000 mt and Russia with 180,000 mt. The only other offers were French, and these were $4 and $10 per tonne more expensive on an FOB basis and also appear to have a $7/mt freight disadvantage making the overall offering around $12 to $18 too much.
  • Very interestingly we received a report from Brazil’s main grain producing state, Mato Grosso concerning their bumper corn crop. It appears that storage facilities are bursting at the seams which, at first glance, may appear good news and highlight their advantageous position in being able to double crop. However, the Mato Grosso Safrhina second crop appears to be at a record 21 million mt, an increase of 18% on last year, and accounts for some 45% of the country’s total crop. The bad news is that the port and road infrastructure is struggling to cope with the volume leaving farmers with crops standing in fields and local prices falling sharply. We have picked up reported levels equivalent to $1.79/bu, which compares with CBOT Dec ’13 at $4.72 today. Crops stored in the open are reported to be a common sight, and buyers are cautious in the extreme. Government auctions have helped to cover the difference between market and world prices, assisting growers and it would appear likely that this will be repeated and by all accounts there will be a large acreage planted next season. Clearly we are living in a very strange world!

29 August 2013

  • Markets closed last night in Chicago looking somewhat easier with EU grains also lower.
  • Brussels granted another big week of wheat export licences with 730,177 mt bringing the season total to 4.127 million mt million mt. This is 2.08 million mt ahead of last years volume, more than double!
  • Stratégie Grains reported on the ongoing UK harvest with winter barley all but complete and spring barley 30% done. Wheat was reported to be 40% harvested. Probably of more significance was their more upbeat estimate of overall output with wheat forecast at 12.25 million mt (194,000 mt up on 15 Jul estimate), barley at 6.875 million mt (60,000 mt up on 15 Jul estimate).
  • German crops are also just about fully harvested with quality reported to be good, however it appears growers are electing to store rather than sell at present. The discount for feed grains compared with milling is reported to be narrowing.
  • The USDA has released its weekly export figures as detailed below:

Wheat; 551,400 mt which is within estimates of 350,000-575,000 mt.
Corn; 658,700 mt which is within estimates of 300,000-700,000 mt.
Soybeans; 865,500 mt which is within estimates of 500,000-1,050,000 mt.
Soybean Meal; 210,000 mt which is within estimates of 110,000-275,000 mt.
Soybean Oil; 24,600 mt which is above estimates of zero to 20,000 mt.

28 August 2013

  • We thought it would be nice to start with some fresh news tonight rather than a rehash of everything that has  been before!
  • Egypt returned the the market for wheat, this time for October shipment, and purchased a total of 295,000 mt. Ukraine topped the sellers with 175,000 mt with Russia and Romania being awarded 60,000 mt each. It appears the only other offer was from France, and about $20 too expensive (or is it that Black Sea offers are too cheap?).
  • We are approaching a long weekend in the US (Labour Day) and with forecasts containing hints of rainfall and cooler temperatures it is entirely possible that we may see something of a retracement in coming days.
  • Newswires are full of “cooler weather” reports, Reuters being a good example; their contribution suggesting lower temperatures into the weekend and remaining cooler next week. The possibility of much needed rainfall over the weekend has also been widely reported.
  • Regardless of speculative weather news, it would seem obvious that the soybean crop in the US is in need of moisture and will also benefit from a reduction in temperature if yield is to be optimised.
  • The Reuters forecasting arm, Lanworth, added their latest forecast today with a corn yield of 152.4 bu/acre resulting in a crop of 13,406 billion bu. Their estimated soybean yield of 40.8 bu/acre results in an output of 3.14 billion bu (2% decline month on month).