23 August 2016

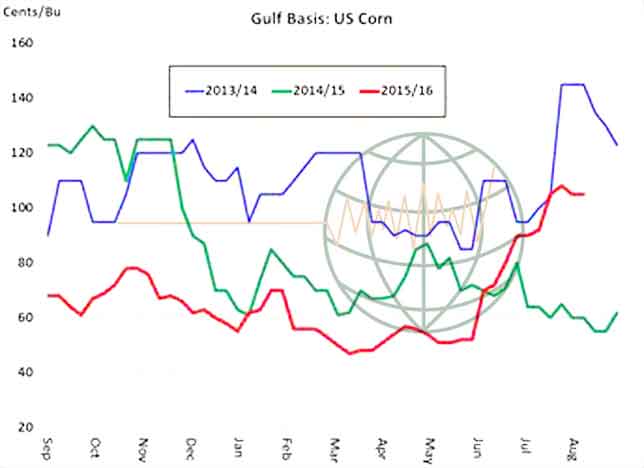
  • Gulf cash corn basis levels continue to rise higher based on an active load out program and a slow start to the Delta corn harvest due to excessive rainfall. As Brazilian corn exports are expected to decline by 15-17 million mt (total depends on final Brazilian corn crop size) and Argentina being nearly sold out of its harvest, the US and Ukraine will battle for world feedgrain demand going forward. We expect that with the Russian and EU corn crops in retreat, and the US corn export profile (which is growing by the day) US corn yields will have to rise above 175 bushels/acre for even weaker corn prices during harvest.

  • After the close last night , NASS reported that 72% of the US soybean crop was rated as either good or excellent, unchanged from last week, and up from 63% last year. Including all crop ratings, the US soybean crop is now the second best rated crop on record. Strong export demand continues to underpin November soybeans, with major moving average technical targets at $10.34 and then $10.45.

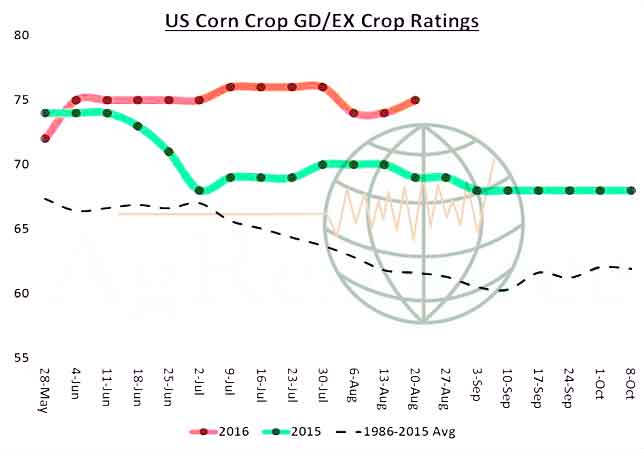
  • NASS also reported that 75% of the US corn crop was rated as good or excellent, versus 74% last week and 69% a year ago. The US corn crop is now the best rated crop on record, for late August. The trade will closely monitor the daily updates from the Pro Farmer crop tour. As noted in tonight’s report, Pro Farmer results have proven to be a good indicator of the USDA’s September crop report. This makes sense, since NASS will begin it’s own crop survey at the end of the month. Technical trading and slightly better than expected demand is offering support for the corn market, with initial technical targets at $3.60-3.70.

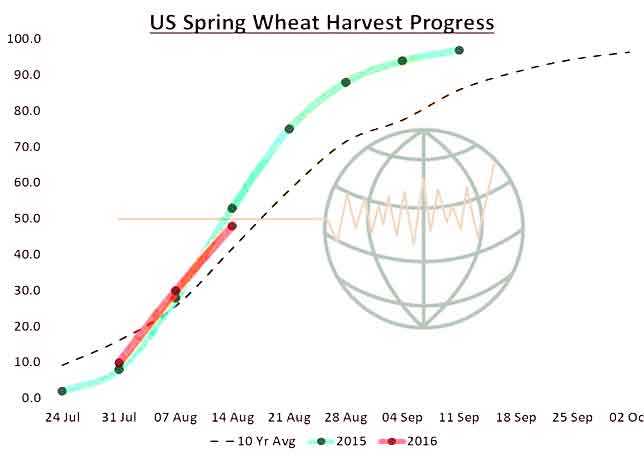
  • The Black Sea is where world wheat prices will be determined and talk that Russia is preparing to halt its export duty until next July was seen as slightly bearish. Although the modest duty was not having much impact on Russian wheat exports to date, the trade well understands that Russia has a huge pile of wheat (27-30 million mt) to export, and that the ending of the duty may produce a bump in domestic cash bids to entice farm sales. Russia does not have the storage to hold a record large wheat and corn crop into the winter and a stepped up producer sales program is expected once the summer row crop harvest commences. US spring wheat harvest advanced to 65% complete versus 48% last week and the 5 year average of 46%. A global cash-led rally looks to continue through autumn, but without major N Hemisphere threats next week rallies look as if they will be tough to sustain.

22 August 2016

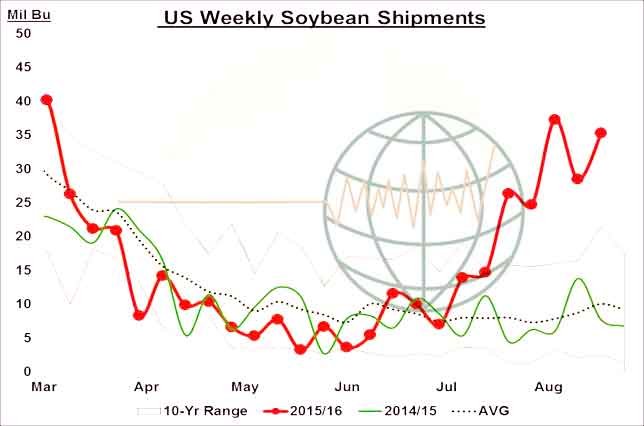
  • Chicago markets saw mixed trade this morning with soybeans making gains as the grains, corn and wheat sagged. It was larger than expected weekly soybean exports that rallied the market to testing $10.15-10.20 basis Nov ’16 futures. The grains were unable to follow where soybeans led. Long soybean vs. short grain trades are featuring today. Any close above $10.21 in Nov ’16 soybeans will likely trigger further chart based buying. The market is very much focussed upon big demand in soybeans and grains are lagging behind on big crop prospects.
  • We have today heard that the Russian Minister of Economy has issued a statement supporting the elimination of there export duty on their wheat exports. It appears that the the odds are growing that by the end of harvest, in mid-September, the duty will be scrapped. Despite the duty not having a substantial impact upon wheat exports, a record harvest of some 72-73 million mt and lack of funds for more than maybe a million mt of intervention purchases will likely continue pressure Black Sea prices. Maybe, just maybe, the duty will return in July 2017 with the new harvest, but Russia is in the throes of becoming even more competitive (and aggressive) in global grain export trade. Consequently, the news is being taken bearishly in both Chicago and EU wheat markets.
  • In summary, US soybean exports were huge for the week ending Aug 18th at 35 million bu. We have cut our 2015/16 US soybean end stock estimate to 225 million bu and 2016/17 to 300 million bu amid a 30 million bu export bump. Thus, a 50 bushels/acre US 2016 soy yield would not hike 2016/17 soy stocks above 400 million bu! This implies that a seasonal low price was scored at $9.43 basis Nov ‘ 6 futures. Our immediate upside target if $10.25-10.40 basis Nov ‘ 6. Corn/wheat have also forged lows, but will likely chop irregularly higher until the summer row crop harvest commences.

18 August 2016

  • Yesterday in Chicago saw soybean markets lower but $10.00/bu support held and prices closed well off the early lows. Products were similarly weaker early on in the session but found support at the session moved on.
  • Corn in Chicago ended higher for the fifth consecutive session again finding support at the lows. Strong demand for US supplies appears the underlying issue as Black Sea cash premiums have rallied to levels above US Gulf. US ethanol blend margins have turned positive amid the ongoing crude and gasoline price rally, which is also supporting corn cash and futures prices.
  • In wheat we note that the US has reportedly sold to Algeria, a traditional French stronghold, which is maybe indicative of the concerns over French crop quality. French and German offers for Nov/Dec have reached $200/mt, the highest level in some 13 months! Chicago fund short positions continue to be pared back and this too is adding support.
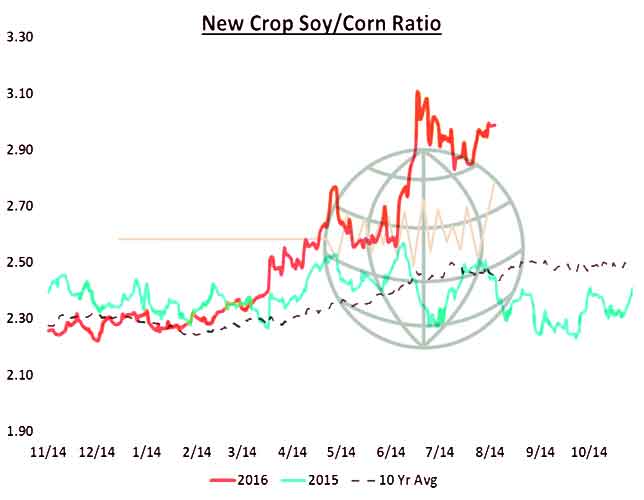
  • The new crop soybean/corn ratio pushed to a high in late June of 3.1:1, and since held in a very wide range, at historically strong levels. The only other year that the ratio has held so strong at this time of year was in 2009. The ratio is often used as a guide to potential acreage shifts ahead of planting, but once crops are planted becomes a function of each commodities individual supply and demand outlook. This year, it’s the record corn yield and the monstrous soybean export demand that has held the ratio at historic levels.

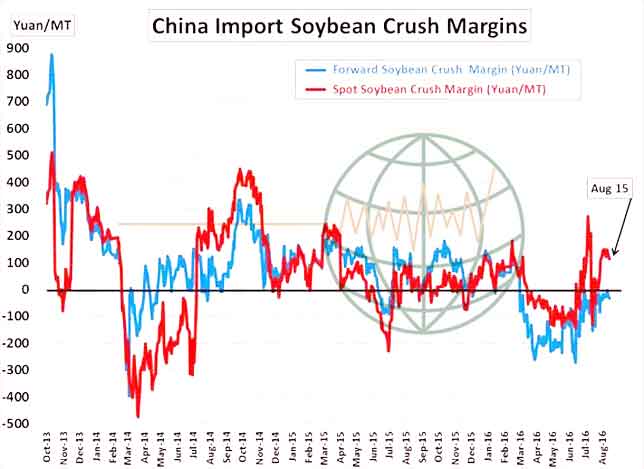
  • Chinese crush margins have recovered to their best levels since February as soybean oil demand/price recovers. The chart below reflects that Chinese crushers are back to making money! Chinese crushers are securing US soybeans trying to lock down domestic margins. We are told that an additional 4 to 6 cargoes of US soybeans sold to China Thursday and for the week to date, China has secured 20 to 25 cargoes. Brazil and Argentina are sold out of old crop soybeans and the US will export record large totals of soybeans through January. It’s this demand for US soybeans that helps absorb record large yield/production.

17 August 2016

  • Chicago markets have once again moved higher with soybean oil providing the initial stimulus as funds added fresh longs in the wake of overnight palm oil firmness. The one story we subscribe to at present is the fundamental bullish tropical oil picture based upon tight Malaysian stocks and good export interest. We can add to this the 2016/17 US soybean oil stock level forecast to reduce to its lowest in many years, despite record large crush rates that are straining capacity. The reduction in US soybean oil stocks together with the improved export demand is the bullish input right now. Technical soybean oil chart patterns are in the process of building a bullish “head and shoulders” pattern, which could well add to upside momentum in the short to medium term.
  • Regardless of supply position in corn and soybeans we are beginning to see a build up in demand for US supplies and this is contributing to support, which will spill over into non-US markets.
  • Soybean oil remains the bullish driver in the near term, but caution should be observed in adding to positions until such time as we see confirmation of growth in US export demand. Price upside is not yet guaranteed!

16 August 2016

  • We have seen Chicago markets trade back and forth this morning and as we approach the close soybeans are a shade down whilst the grains, corn and wheat are just in positive territory – a “non-day”. Crude oil, which is a little firmer is having a positive influence and the potentially large US summer row crops, which are only just around the corner suggest that caution should be adopted when making large purchases. Further US soybean sales to China have been noted and one can only wonder how much they will chase prices should they continue higher given the potential for a record large US crop.
  • On the subject of China, it is reported that their government will halt reserve corn and soybean stock auctions in early October. The point being that if China is serious about shifting old crop stocks it will have to become more aggressive as far as prices are concerned in coming weeks, which could pressure prices.
  • Weather prospects appear to be improving for pressured farmers in Germany and Poland, and the next ten days appears to offer a window of harvest opportunity. Their harvests have struggled over the past few weeks amid frequent rain showers, which have harmed quality and yield, and the forthcoming window should help harvest progress more strongly. Additional downgraded (to feed) wheat is the last thing required within the EU market at this time. Germany’s feed coops are forecasting their 2016 wheat crop at 24.21 million mt, some 8.8% below last year’s record output.
  • Next week sees the start of the influential US Pro Farmer crop tour and it will be interesting to see if they validate the US’s latest yield estimates in corn and soybeans. We see little to trigger either bullish or bearish price trends until such time as we see the start of mainstream US harvest activity.

15 August 2016

  • Chicago markets have been a deep shade of green this morning as fund short covering in the grains and end user pricing in soybean oil added support. Tropical veg oils have trended higher on tightening global supplies and strong global demand. And this has led the Chicago soybean complex higher.The oil share in the soybean crush calculation has grown to 34%, close to the 38% it reached earlier in the year. A strong close tonight will add conviction to our belief that August lows have been scored.
  • Chicago is today focussing on demand as we suggested would eventually become the case; however, we would caution against chasing the rally as demand led bull markets usually provide an entry point at some stage!

11 August 2016

  • Brussels has issued weekly wheat export certificates totalling 491,794 mt, which brings the season total to 3.289 million mt. This is 801,015 mt (32.19%) ahead of last year. Barley exports for the week reached 49,810 mt, which brings the season total to 881,149 mt, which is 1.08 million (55.07)% behind last year.
  • The USDA has today released its weekly export figures as detailed below:

Wheat: 607,600 mt, which is above estimates of 350,000-550,000 mt.
Corn: 1,610,500 mt, which is above estimates of 1,000,000-1,500,000 mt.
Soybeans: 3,100,200 mt, which is above estimates of 2,100,000-2,900,000 mt.
Soybean Meal: 98,400 mt, which is within estimates of 90,000-450,000 mt.
Soybean Oil: 12,500 mt, which is within estimates of 10,000-35,000 mt.

  • Chicago soybeans have caught a bid on the back of significant export volume data released today as well as fresh daily sales announcements, whilst the grains are languishing on spreads and long profit taking ahead of tomorrow’s August report. Grains volume is reported to be high and the current thinking is that farmer selling is responsible as growers clear corn stocks ahead of the report, US farmers were believed to be sitting on large corn volumes and looking for buyers.
  • Stratégie Grains’ latest 2016 EU soft wheat crop estimate is once again lower month on month at 137.9 million mt, which is 7.7 million mt behind last month and 9% down year on year. Their corn estimate is also reduced to 60.6 million mt, a full 1.1 million down month on month and 6% behind last year. The downgrade in wheat output is on account of French woes, added to which German prospects are also reduced. On a slightly better note UK output was predicted to be 14.8 million mt a mere 200,000 mt behind last month’s estimate, and early harvest quality is looking better than earlier thought.

10 August 2016

  • Today we have seen pre report positioning take the front spot with grains catching a bid whilst soybeans turned lower as the Nov ’16 contract tested the psychologically important $10.00/bu level and price action reversed yesterday’s trends. The lack of soybean sales announcements to China, after ten consecutive days of sales, created some profit taking and the stronger US$ helped the grains higher.
  • We would expect to see a continuation of strong export sales announced on Thursday with soybeans potentially above 2 million mt and corn in the 1.3-1.6 million range.
  • News continues to circulate regarding heightening Russian/Ukrainian tension in Crimea, and the potential impact on grain markets should not be ignored. At this time there is no evidence of any risk premium in prices.
  • 2015/16 full season UK wheat exports reached 2.85 million mt, the highest since 2008/9.
  • Little else in the way of fresh news today as the markets await Friday’s data release from the USDA.