6 January 2015

  • Rumour and counter rumour continues to dominate markets in the post holiday trading period as we lead into next week’s USDA report. Today’s US rally in wheat (which did not follow through to the close) was based on rumours that Russia had followed Ukraine in stopping VAT reimbursement on exports. MATIF closed flat as some “traders” (always nameless!) cited switching into corn from wheat as the reason because corn had more upside potential – dumb and dumber springs to mind!
  • Early trade saw an attempt at “Turnaround” as we suggested yesterday, but concern over coming extreme cold in S Midwest soft red wheat areas put an end to that. We are told there is adequate snow cover, but fears still exist over winterkill (unjustified we are told).
  • Other news is thin apart from a few fresh crop estimates, which includes Informa Economics’ latest figures. They peg the 2014 US corn yield at 172.7 bu/acre, below the last USDA figure of 173.4 bu/acre. Soybean yield was estimated at 47.6 bu/acre vs. USDA at 47.5 bu/acre. Their estimate for harvested corn acres rose to 83.527 million which is430,000 above the USDA. 2014 corn output was estimated at 14,425 million bu, 18 million above the USDA’s November figure (no Dec estimate). 2014 soybean production was put at 3,969 million bu, an increase of 11 million on the USDA’s November figure.
  • There were no real surprises in the Informa figures, some raised an eyebrow at the rise in corn harvested acres, however we did suggest some while ago that the “official” data was incomplete this year and subject to revision – in time.
  • Informa also estimated Brazil’s 2014/15 corn crop at 72.25 million mt, an increase of 3 million mt month on month. The Ukraine 2014/15 crop was also increased month on month, by 1.5 million mt to 28 million mt.
  • Finally, the post holiday catch up in EU wheat export licences shows that 987,741 mt of certificates granted over the two week period. This brings the season total to 15.453 million mt, which is 352,261 mt (2.3%) ahead of last year.

5 January 2015

Markets moved higher to start the first full week of 2015 in some sort of response to the 2014 year end drubbing although the fundamentals continue to point lower. There was presumably some post holiday euphoria in Chicago, interestingly many of the buyers were last week’s sellers! Front month Jan ’15 soybeans pushed back to the 50 day moving average, wheat remains well below December highs whilst corn has clawed back around half of last week’s losses. Will the first Tuesday in 2015 display classic “Turnaround” tendencies?

Matif wheat bounced to close at seven month highs supported by a nine year low in the €uro and suggestions that last week’s Algerian tender saw in excess of half a million mt sold at a price believed to be at or very close to full replacement. Black Sea prices for Russian origin wheat were well supported with shorts prepared to pay up of January shipment in order to beat the February tariff deadline. There is also news that Ukraine has decided to halt VAT reimbursement, which when added to the severe cold forecast for the US all added support. One piece of good news lies in the reported level of EU/Black Sea snow cover which is shown on the attached graphics and appears significantly better than a year ago.


S American weather continues to attract discussion, as would be expected now that the US is done and dusted – all bar final counting. There is some dryness in Bahia (far NE Brazil) which accounts for around 4 million mt of soybean production. The remainder of Brazil and primary crop producing regions of Argentina have enjoyed near to above average rainfall and a lack of any real heat. The bottom line is that the crop has potential for record yield, and like the US crop now requires some “finishing” rain to allow it to mature. There will be a requirement for dry weather across N Brazil post 25 January to allow harvest to progress speedily.

It is reported that China is to hold an auction for some of its 5 million mt (???) reserve corn stocks, and there is an expectation that this may well encounter difficulties due to the age of the stock (2 – 3 years old) and the fact that it is stored outdoors! If demand for their stock is limited it will impact China’s issuance of import licences negatively limiting the volume of exports from the majors, US and Brazil.

It has already been an interesting start to the year.

23 December 2014

  • Brevity is the word! Today was supposed to be the day Russia clarified its intentions on exports but all we got was more rumour. Suggestions that an export tax as high as €100/mt on all grains – with immediate effect was probably the best of the bunch! Clearly, the impact of such a move would be the immediate cessation of all Russian grain exports. We would not recommend trading on the back of such a rumour bound market, await the facts.
  • Reuters forecasting arm, Lanworth, issued its latest 2014/15 projections as follows:

World corn output 1,005 million mt, which is 13 million mt above the current USDA number.
World soybean output 320 million mt, which is 7 million mt above the current USDA number.
World wheat output 715 million mt, which is 7 million mt below the current USDA number.
World rapeseed output 70 million mt, which is 2 million mt below the current USDA number.

  • They did highlight that their numbers may well change based upon planted acreage, which is highly likely to change due to fluctuations in commodity prices in current volatile times.
  • Trade volumes are reducing to very low levels ahead of the holiday period, many are already on holiday and not planning to return until the new year. MATIF markets close at midday as does CBOT (local time).
  • Thank you for all your support in 2014 and we hope you have a safe, happy and festive Christmas and a prosperous New Year.

22 December 2014

  • After the close on Friday Egypt tendered for wheat once again. They ended up paying their highest purchase price in some seven months and secured 300,000 mt with all but 60,000 mt from France. Russia picked up the remaining cargo with what turned out to be just one offer. France offered more than was purchased potentially signalling better availability than has been previously thought. The USA soft red wheat offer was notable by its price, which was some $40.00/mt above the best French clearly signalling its total lack of competitiveness.
  • Egypt has now purchases more than 2.9 million mt so far this season and France has secured the bulk of this at just over 1.1 million mt. Potentially the aggressive French sales have resulted from the Egyptian specification which is below that of another of France’s key customers, Algeria.
  • Russian wheat continues to dominate the news with early trade digesting all that had hit the headlines last week and a feeling that “the worst was over”. However, news that an export tax rumour on Friday had become a quasi-fact on Monday added to market confusion and early losses were regained (although late trade saw the CBOT market close over 1% lower). Is the tax a replacement for the phytosanitary and rail issues of last week, or an additional measure? No-one seems to know the answer right now – and more importantly no-one in Russia is letting on! The level of tax is unclear, whether it will only apply to new sales is unknown and to which products it will be levied is also a mystery. The situation is a complete mess!
  • The outcome could well be along these lines; 1) Russian domestic prices ease allowing government intervention purchases to be made. 2) The world (at last) realises that the “lost” export volume from Russia is only about 3 or 4 million mt and the rest of the world, and EU in particular, can take up the slack. 3) Prices ease as the current risk premium is seen to be overdone. 4) Russia returns to the export market (possibly to late to be effective) and markets decline still further. This is only a thought, and may turn out to be pure fantasy!
  • US soybean exports for the week ending 18 December were, once again, well above expectations as well as the pace required to reach the USDA’s annual forecast. Corn exports however were below expectation and wheat numbers were unsurprisingly light. The soybean market picked up on the data whilst corn read the numbers as somewhat bearish. In the US markets have ample supply and each CBOT rally is eliciting producer selling which is, in turn, easing cash basis and pointing towards the tail off in US export demand – particularly in soybeans. The S American soybean harvest, which we hear has just got under way and will speed up into January, still looks to be big and possibly record large. Weather patterns continue to be favourable although it is reported that some additional sunshine would benefit crops in N and C Brazil.
  • As we move towards the Christmas break markets appear to lack both direction and volume. Funds appear happy to protect longs although cash markets seem to be very vulnerable on volume producer selling and good volume availability.

18 December 2014

  • CBOT markets are all approaching the close in positive territory although wheat is well off its daily high. London wheat also saw a huge (by London standards) trading range with May ’15 spanning £8.00/mt before closing at the lows of the day and also lower on the day.
  • MATIF wheat (Jan ’15) is now trading at a premium of £22.45 to its London counterpart having been a single digit premium not too long ago. The value of milling grade wheat is beginning to make its mark – at last!
  • The USDA has today released its weekly export figures as detailed below:

Wheat: 509,400 mt, which is above estimates of 250,000-450,000 mt.
Corn: 698,400 mt, which is within estimates of 650,000-850,000 mt.
Soybeans: 1,046,000 mt, which is above estimates of 600,000-800,000 mt.
Soybean Meal: 146,800 mt, which is above estimates of 0-100,000 mt.
Soybean Oil: 38,800 mt which is above estimates of 5,000-20,000 mt.

  • Brussels issued weekly wheat export certificates totalling 567,797 mt, which brings the season total to 14,465,402 mt. This is 436,720 mt (3.11%) ahead of last year’s record pace.
  • Other data releases today came from Brazil with Abiove raising its estimate of their 2014/15 soybean crop by 900,000 mt to 91.9 million mt. The Argentine AgMin put their 2014/15 wheat  crop at 13.2 million mt, which is a 1.2 million mt uplift from the last estimate. They also increased the 2014/15 soybean area by 100,000 ha to 20.2 million ha.
  • In the aftermath of yesterday’s “market carnage” following the quasi ban on exports by Russia we have seen some consolidation and acceptance of the situation, and risk is now costed into prices, The USDA has issued its 2015/16 baseline crop estimates which, as ever, gave little cause for eyebrow raising. However, one number did raise a question, and that is the overall reduction of 3.8 million acres in total cropped area. Given relatively high prices at present this seems something of an oddity, but that aside the projections appear to affirm the longer term bearish trend if assumed trend yield proves correct – and at this early stage it would be unwise to assume anything else!

17 December 2014

  • Despite our earlier thoughts it appears that we now have a de facto ban on exports of Russian grain due to phytosanitary certificates being refused to all but Egypt, Turkey, Syria, Armenia and India. Bear in m ind Egypt and Turkey took 7 million mt between them last year out of the 18.5 million mt of total wheat exports. Syria, Armenia and India are on the list but account for minimal tonnage and appear to be a political gesture rather than anything else.
  • Some 15 million mt has been shipped through to mid-December, and there is a risk that some 7 million mt, based on the USDA’s full year export estimate, is at risk – less anything else that can be exported to Egypt or Turkey. The trade is staring default and force majeure all over the place and one thing is clear, and that is that huge sums of money will be lost. One other point should not be missed, and that is that Russia is still living in the old Soviet era, and has not come to terms with today’s modern world and the way is operates. Regrettably, memories are all too short, and next year most will doubtless “forget” and business will resume “as usual”.
  • Unusually, loaded vessels are currently prohibited from sailing, further compounding problems for shippers, traders and receivers alike. Egypt’s response was one of “confidence that Russia would fulfil its obligations”, and stated that Russia would remain as an origin for further tenders. Further commentary from elsewhere has affirmed thoughts that sufficient wheat remained in alternate origins to ensure the grain did not succumb to any shortage or suggestions of such.
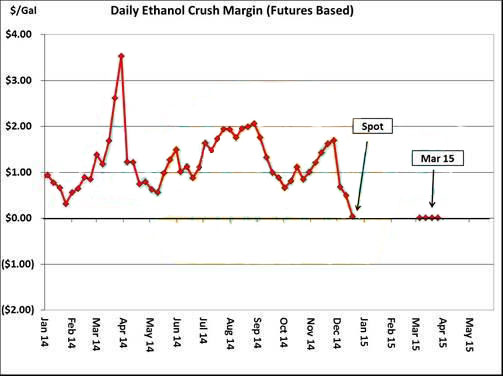
  • Away from Russian wheat, it appears that US ethanol producers are to shortly follow in the footsteps of their EU counterparts as a consequence of the sharp fall in crude oil and unleaded gasoline prices.
  • The chart shows that marginal profitability exists today but  by the end of Q1 current corn and ethanol prices will put margins into the red. Blender margins in the US are already negative and the incentive to grind more and more corn appears to be dissipating slowly but surely. The current oil oversupply position looks set to last, possibly for some years, and the ethanol producer’s profit incentive has been cut – significantly from where it has been in recent months.

16 December 2014

  • Headlines from both Reuters and Bloomberg suggest that China is on the verge of approving MIR162 corn in the near future. Whilst there is no date or time reported, it coincides with the Chinese delegation visiting the US at present. Headlines suggest that 2 to 2.5 million mt of fresh US corn demand could arise from any approval, in addition DDG export demand could well increase to 150,000-350,000 mt/month which would offset some of the recent Turkish lost business following discovery of GMO material almost two weeks ago.
  • Russia’s AgMinister remains tough talking against Russian wheat exports; no official ban has been announced but fears continue to grow that restrictions could be imposed as intervention stocks are rebuilt. The Rouble managed to bounce following a massive decline to 80:1 vs. US$, the Russian Central Bank raised its overnight borrowing rate to 17% from 10.5%, but fears still abound that severe recession will hit the country lasting well into 2015. News that Russian intervention price is to rise to 10,100 Roubles/mt from 6,750 Roubles/mt did little as the new price remains well below current domestic cash bids. There is a glimmer of hope that crude oil is forging a bottom, temporary or otherwise, and talk of a $50 low is rife.
  • In Brazil the Real reached 2.75:1 vs. US$ and farmers were huge sellers of new crop soybeans and corn, volumes are reported to be the biggest since March earlier this year when the harvest was in full swing. The decline in the value of the Real has elevated soybean values to close to last year’s levels – enough for farmers to say, “Thank you!”
  • In Chicago today the wheat/corn spread reached $2.25 wheat premium on the back of concerns over Russian supplies but global surplus stock should keep further upside in the spread limited. Front month spreads may well widen a touch, but relative values appear to have reached a level from which it is difficult to see much more upside.
  • In Europe cash soybean meal was as much as $10 down today, from Monday, on the back of easing S American cash markets. Buyers were not very much in evidence on the break as the expectation is for further easing in prices as market fundamentals become more influential. Cash premiums for soybean meal in central US are, without doubt, easing – and fast, By comparison January soybean meal from Paraguay is offered at about $57/ton below comparable US Gulf levels whilst Mar/May Paranagua is currently about $55 below the Gulf. These price levels point to US exports losing competitiveness and a slowdown in volumes will likely follow.
  • Ukraine corn was offered into northern EU/UK/Eire at €167, this is around €15 below French and it is becoming clear that suggestions of limited Ukrainian corn supplies are incorrect!
  • In conclusion, there appears to be increasing evidence that global currency issues (Russia, Ukraine, Brazil – to name but a few) argue strongly for large acreage increases and deflation-led demand reduction. As a consequence, growing global stocks will see further additions and the ags look set for a return of the bear trend.

15 December 2014

  • In a slight diversion from our usual format we thought it worth passing comment on the implications of the recent drop in crude oil prices. Ethanol production remains profitable in the US, according to our sources, but is under some pressure within the EU. Despite this, there is a suggestion that EU ethanol has recently been sold to S America at a more competitive level than US material, but further crude declines will impact EU production before it does the same to US. If that becomes the case there will be a knock on impact upon wheat prices, physical as well as futures, and that would be a negative impact (as if that needed fleshing out!).
  • The current uplift in wheat prices caused largely as a consequence of fears over availability of Russian supplies is already putting pressure on the EU ethanol industry and prices in coming days and weeks will have to be monitored closely. Additionally, the higher prices have created a technically supportive platform from which further buying has emanated. As we have stated previously, by the time any restriction on Russian trade could be put in place it would only be the last 2 or 3 million mt of annual exports that would be impacted, and therefore of minimal disruptive impact to global trade. As such, the market premium which is now in place feels to us to be excessive right now.
  • An overview of Russia today shows a further 11% drop in the Rouble today, 90% since the summer, and crude oil dropping below $56. Confidence in Russia is at its lowest ebb form many, many years and will surely take a long time to be restored. Investment will be limited and trust similarly difficult to establish, there are few, if any, takers on Russian wheat cash offers that are around right now.
  • In corn, there is a split of view as to whether (or not) China has, or is about to, approve the GM event MIR162. Regardless of the actuality, China has too much corn in its domestic stockpiles, at prices well above global levels, to permit unfettered access to cheap (in relative terms) imports. They will surely find another GM event or phytosanitary reason to curtail volume imports whilst maintaining an aura of free access.
  • Corn in Europe ended higher as a result of CBOT and MATIF wheat, Ukraine corn looks very competitive into the EU although establishing definite prices is somewhat difficult in practice. The Hryvnia hit new all-time lows and reports of defaults on cargoes to China continue to circulate. In an already difficult market the added complexity of plantings next year being maxed out due to the exchange rate looks set to become a reality.
  • Soybean and product bulls are eagerly awaiting pronouncements from the Chinese delegation currently visiting the US. It is expected they will sign frame contracts, which from our understanding, have little commercial relevance as they contain no performance or penalty clauses; they are simply a memorandum of intent and should not be market moving. Given the imminent availability of a large (if not record) S American soybean harvest it feels as if we should see limited price upside from here on in.
  • Markets in the run up to Christmas and year end don’t appear to offer much to make life any easier!